Errante’s The Week Ahead: 16th – 20th December 2024
What Now?
Errante’s The Week Ahead: 16th – 20th December 2024. This week’s spotlight falls on inflation and growth data, with UK CPI, US GDP, and Core PCE figures taking center stage. In the UK, CPI year-over-year data is expected to remain steady at 2.3%, but any surprises could have significant implications for the BoE’s monetary policy meeting later in the week. A softer print may bolster dovish expectations, weighing on the pound, while stronger inflation could complicate the BoE’s policy path.
In the US, the Final GDP print for Q3 is expected to confirm robust economic expansion at 2.8%. The resilience of the US economy, underpinned by strong labor markets and corporate optimism, continues to contrast sharply with weakness in Europe and parts of Asia. Markets will also watch the Core PCE Price Index, forecast at 0.3% m/m. As the Fed’s preferred inflation gauge, this data will play a critical role in shaping rate expectations for 2025.
Market Events and Announcements:
Times are in GMT+2.
Times are in GMT+2.
Monday, December 16, 2024:
10:15 AM – EUR: French Flash Manufacturing PMI and Services PMI: Early indicators of economic activity in France, providing insights into the health of the manufacturing and services sectors.
10:30 AM – EUR: German Flash Manufacturing PMI and Services PMI: A barometer for Europe’s largest economy, offering critical clues about broader eurozone trends.
11:30 AM – GBP: Flash Manufacturing PMI and Services PMI: Key measures of UK economic activity, shaping expectations for BoE policy.
10:20 PM – CAD: BOC Gov Macklem Speaks: Commentary from the Bank of Canada governor could influence CAD sentiment ahead of inflation data.
Tuesday, December 17, 2024:
9:00 AM – GBP: Claimant Count Change: Early insight into UK labor market conditions.
3:30 PM – CAD: CPI m/m, Median CPI y/y, and Trimmed CPI y/y: Critical inflation data impacting the Bank of Canada’s outlook.
3:30 PM – USD: Core Retail Sales m/m and Retail Sales m/m: Indicators of consumer spending strength in the US.
Wednesday, December 18, 2024:
9:00 AM – GBP: CPI y/y: A key inflation measure for the UK, expected to remain at 2.3%. Surprises could influence BoE decision-making.
9:00 PM – USD: Federal Funds Rate, FOMC Economic Projections, and FOMC Statement: Highly anticipated Fed policy update with significant market implications.
9:30 PM – USD: FOMC Press Conference: Jerome Powell’s commentary on the Fed’s economic outlook and policy trajectory.
11:45 PM – NZD: GDP q/q: A quarterly measure of New Zealand’s economic performance.
Thursday, December 19, 2024:
Tentative – JPY: BOJ Policy Rate, Monetary Policy Statement, and Press Conference: Key insights into Japan’s policy stance.
2:00 PM – GBP: Monetary Policy Summary, Official Bank Rate, and MPC Official Bank Rate Votes: Critical updates from the BoE.
3:30 PM – USD: Final GDP q/q and Unemployment Claims: Additional data on US economic growth and labor market conditions.
Friday, December 20, 2024:
9:00 AM – GBP: Retail Sales m/m: A measure of UK consumer spending.
3:30 PM – CAD: Core Retail Sales m/m, Retail Sales m/m, and Core CPI Index m/m: Canadian data to end the week. Additionally, at the same time, USD: Core PCE Price Index m/m: expected at 0.3%, a critical measure of inflation influencing Fed decisions.
Market Insights: Key Charts to Watch
Chart 1: GBP/USD – Daily Chart
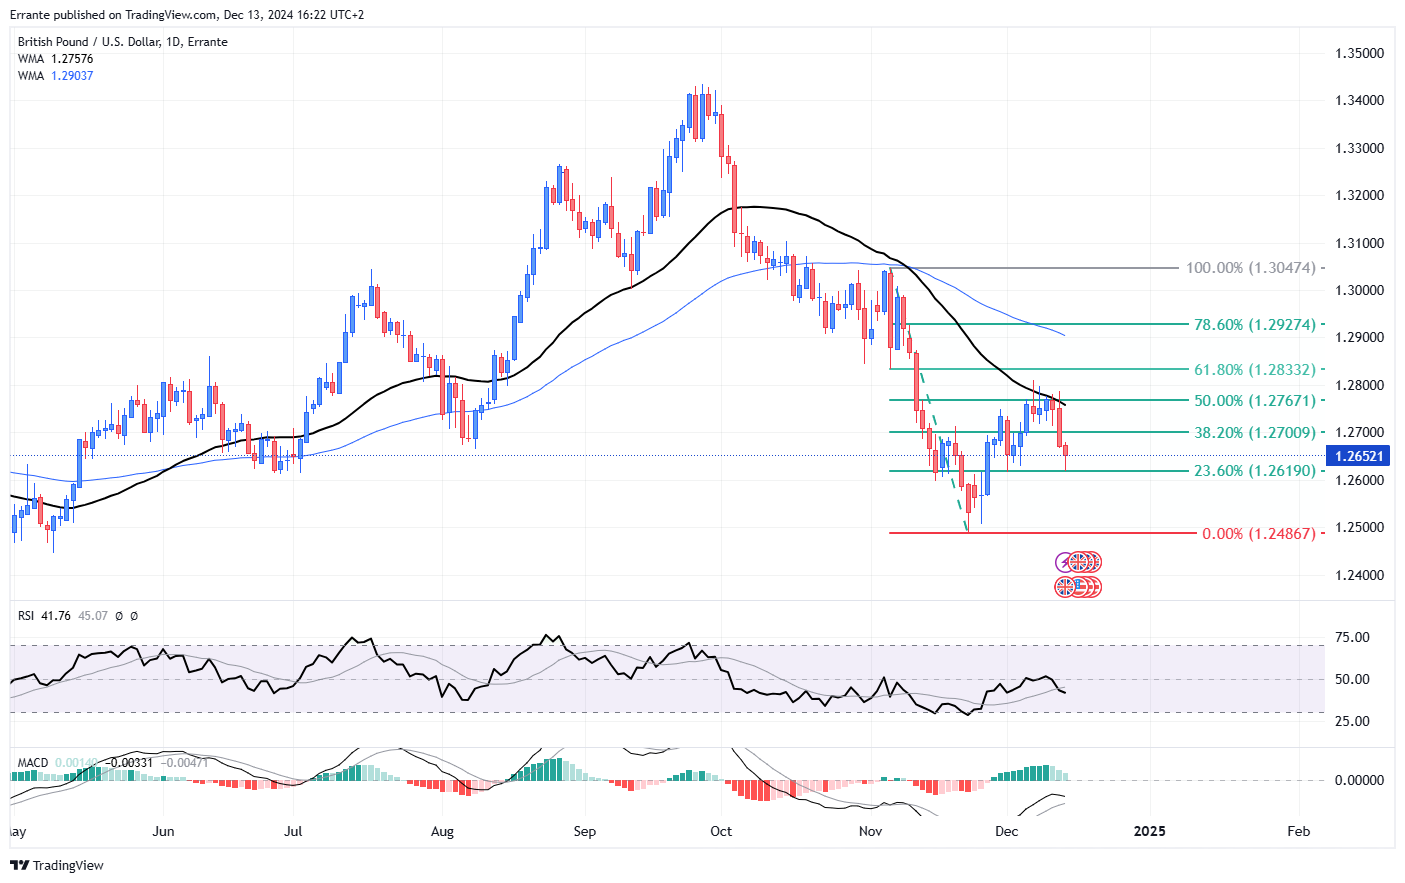
GBP/USD is under renewed pressure, trading around 1.26521 as markets digest the impact of soft UK economic data and BoE policy expectations. After failing to sustain a rebound above key Fibonacci retracement levels, the pair is vulnerable to further declines.
Chart 1: GBP/USD – Daily Chart
GBP/USD is under renewed pressure, trading around 1.26521 as markets digest the impact of soft UK economic data and BoE policy expectations. After failing to sustain a rebound above key Fibonacci retracement levels, the pair is vulnerable to further declines.
Main Scenario:
A decisive break below 1.26190, the 23.60% Fibonacci retracement, could see the pair target 1.24867—its recent low. The pair remains in an established downtrend, with technical indicators favoring a bearish scenario. However, as we approach critical central bank rate decisions, market dynamics could shift. The BoE is expected to keep rates unchanged, while the Fed is projected to cut rates, which could provide a temporary rebound for the GBP, allowing it to test higher resistance levels, such as 1.27009 and 1.27671.
A decisive break below 1.26190, the 23.60% Fibonacci retracement, could see the pair target 1.24867—its recent low. The pair remains in an established downtrend, with technical indicators favoring a bearish scenario. However, as we approach critical central bank rate decisions, market dynamics could shift. The BoE is expected to keep rates unchanged, while the Fed is projected to cut rates, which could provide a temporary rebound for the GBP, allowing it to test higher resistance levels, such as 1.27009 and 1.27671.
Alternative Scenario:
A recovery above the 38.20% Fibonacci level at 1.27009 may allow the pair to retest 1.27671 and the 50.00% retracement level. Sustained momentum above 1.28332 is required to alter the bearish narrative.
A recovery above the 38.20% Fibonacci level at 1.27009 may allow the pair to retest 1.27671 and the 50.00% retracement level. Sustained momentum above 1.28332 is required to alter the bearish narrative.
Impactful Events:
The BoE’s rate decision and UK CPI data will dictate the pair’s trajectory. Weak inflation or a dovish BoE could trigger a test of lower levels.
The BoE’s rate decision and UK CPI data will dictate the pair’s trajectory. Weak inflation or a dovish BoE could trigger a test of lower levels.
Key Levels:
Support: 1.26190, 1.24867
Resistance: 1.27009, 1.27671, 1.28332
Support: 1.26190, 1.24867
Resistance: 1.27009, 1.27671, 1.28332
Chart 2: US 10-Year Treasury Yield – Daily Chart
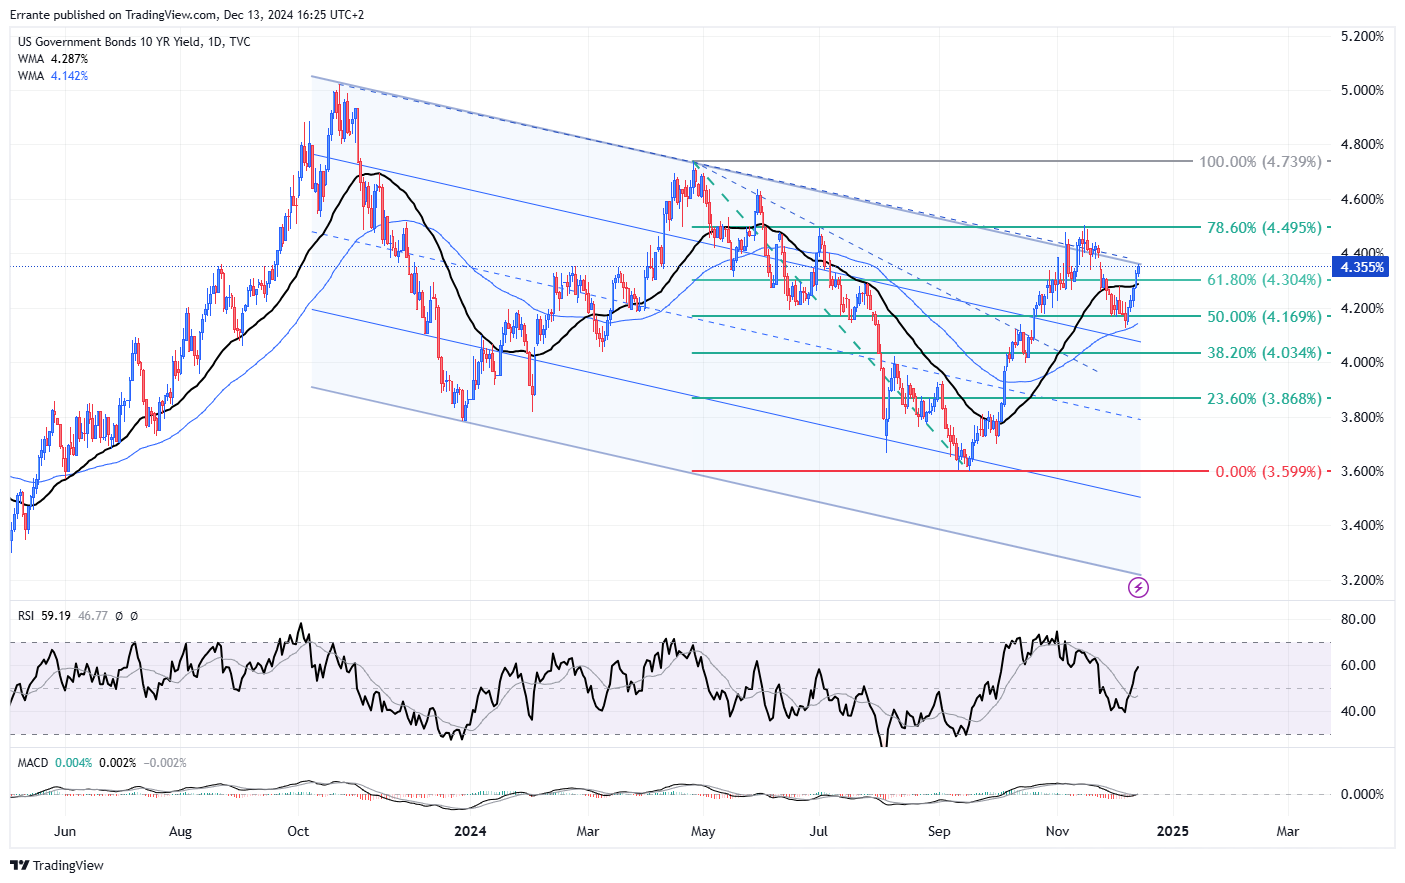
US Treasury yields continue to reflect the market’s expectations for Fed policy. Currently trading at 4.355%, yields have bounced off recent lows as markets reassess the timing and extent of future rate cuts.
US Treasury yields continue to reflect the market’s expectations for Fed policy. Currently trading at 4.355%, yields have bounced off recent lows as markets reassess the timing and extent of future rate cuts.
Main Scenario:
A sustained move above 4.304% (61.80% Fibonacci retracement) could see yields test 4.495% and potentially break higher, signaling renewed confidence in US economic growth.
A sustained move above 4.304% (61.80% Fibonacci retracement) could see yields test 4.495% and potentially break higher, signaling renewed confidence in US economic growth.
Alternative Scenario:
A reversal below 4.169% (50.00% Fibonacci level) would shift the focus back to 4.034%, with further downside possible if market sentiment deteriorates.
A reversal below 4.169% (50.00% Fibonacci level) would shift the focus back to 4.034%, with further downside possible if market sentiment deteriorates.
Impactful Events:
The Fed’s rate decision and Powell’s press conference are pivotal. Hawkish guidance could drive yields higher, while dovish commentary may reignite bond buying.
The Fed’s rate decision and Powell’s press conference are pivotal. Hawkish guidance could drive yields higher, while dovish commentary may reignite bond buying.
Key Levels:
Support: 4.169%, 4.034%
Resistance: 4.304%, 4.495%
Support: 4.169%, 4.034%
Resistance: 4.304%, 4.495%
Publication date: